Common mistakes to avoid when starting an accommodation business
Featured content
Starting a guest house is an exciting venture but comes with specific challenges you might not expect. Many new owners enthusiastically enter the hospitality sector but soon discover that the rules differ significantly from those of a traditional residential property. Whether buying a ready-to-run property or converting an existing one, avoiding common errors early on gives you the best chance of running a successful, profitable business.
Mistakes When Financing Your Guest House
One of the most common problems occurs during the mortgage application process. Guest house mortgages differ from standard home loans in several ways, especially in how lenders assess your income and the property. Using the wrong type of mortgage, such as a residential product, can lead to penalties or even forced repayment if the lender finds out you’re running a commercial operation.
You need to apply for a guest house mortgage that is tailored for mixed-use properties, which are often your home, and a business combined. These mortgages consider seasonal income, occupancy trends, and your business plan. Lenders expect a detailed view of your expected income and costs, not just payslips. Without this, your application may be rejected or have stricter terms and higher deposits.
Planning Issues and Property Classification
It’s easy to overlook planning regulations when transforming a home into guest accommodation. Most guest houses require a change of use to Class C1 or similar. Skipping this step delays your project and limits your mortgage options. You must also factor in listed building status or local authority restrictions, especially in popular areas like Bath and Somerset.
Facilities also need to reflect guest expectations. Accessibility is important if you’re targeting older visitors, and outdoor enthusiasts might expect storage space for gear. These details affect approval processes and guest satisfaction, so tailoring the space from the beginning helps avoid setbacks.
Health and safety compliance is another hurdle. Fire doors, clear escape routes, certified systems, and food hygiene approval are not optional, they are essential. If you skip these, you risk delays, fines, or closure.
Gaps in Trading History and Financial Projections
If you’re a new operator, lenders will likely see you as a higher risk. You may face higher deposit requirements or stricter lending conditions without at least two years of trading records. However, you can strengthen your application with a thorough business plan and by demonstrating your industry knowledge.
Working with experienced partners can also boost confidence. Some lenders offer specialist products for first-time operators, though these often come with higher rates or borrowing caps. It’s important to be realistic about the time it will take to break even and build a strong financial forecast that accounts for fluctuations throughout the year.
Underestimating Startup and Ongoing Costs
You might focus too much on cosmetic changes without budgeting for essential upgrades like fire safety improvements or ensuite conversions. These costs quickly add up, especially in areas with older properties.
Don’t forget the ongoing expenses either. Business insurance, safety certificates, regular maintenance, and cleaning services can cost thousands annually. If you provide extras like meals or group bookings, premiums often increase. Without a clear picture of your operating costs, it’s easy to find yourself short of funds before you’ve built a customer base.
Seasonal shifts must also be included in your planning. Guest house mortgage lenders want to see that you’ve accounted for slower periods, not just the busy season. Keeping a cash buffer will help you manage off-peak months without struggling to cover bills.
Business Plan and Marketing Missteps
Many owners treat the business plan as a formality, but it’s one of the most important tools for securing funding. You need to explain who your ideal guest is and how your facilities, pricing, and marketing approach meet their needs. A generalised plan without a target market makes lenders wary.
Pricing errors are common. Charging too little to attract bookings can lead to losses, while rigid pricing ignores demand changes. Use local research to set competitive but profitable rates. Your marketing approach matters too. Relying solely on third-party sites eats into profits. Developing direct booking options and clear marketing strategies shows lenders you’re serious about long-term success.
Mistakes in Profit Forecasting
Your ability to repay a guest house mortgage depends on your profitability, and that’s where EBITDA (earnings before interest, tax, depreciation, and amortisation) comes in. Accurate forecasts need to reflect all expected costs and income. You should clearly show how your figures were calculated, factoring in variables like booking commissions and seasonal occupancy changes.
Avoid overly optimistic projections that assume every room will be filled every night. Instead, use conservative estimates that reflect the realities of your market. This gives lenders confidence that you understand the risks and can handle downturns.
Insurance and Legal Oversights
A basic home insurance policy won’t cover your guest house. You’ll need commercial policies including public liability, employer’s liability (if you have staff), and business interruption insurance. These are often mandatory for mortgage approval and critical for protecting your investment.
You also need to comply with data protection rules. If you store guest information, you must register with the Information Commissioner’s Office. Booking systems must be secure, and your staff should be trained on privacy rules. Overlooking this can result in fines and a loss of customer trust.
Setting Yourself Up for Success
Starting a guest house takes more than just enthusiasm. Success depends on understanding your responsibilities, being realistic about costs, and choosing the right financial products. Avoid shortcuts and focus on building a strong foundation. This means choosing appropriate insurance, ensuring regulatory compliance, and preparing a detailed business plan. With careful planning, you’ll improve your chances of securing the right support and building a profitable accommodation business.
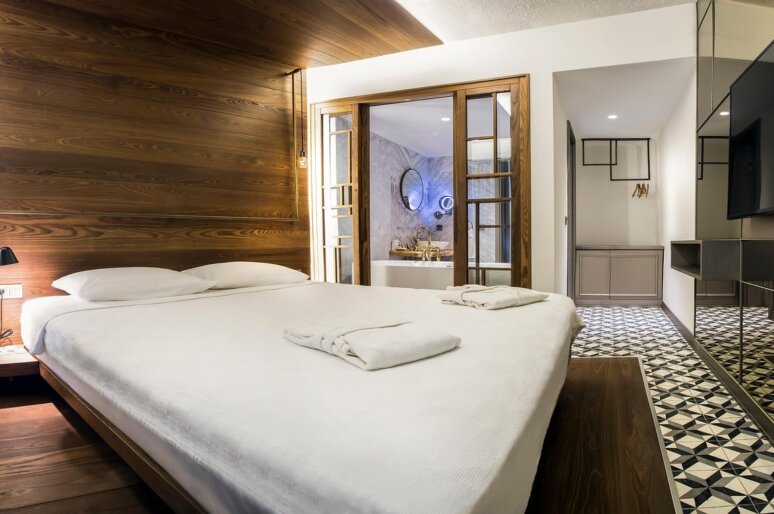
Pictured above: Image by burakyamanlica from Pixabay